Due Diligence: What a Buyer Actually Checks Before Wiring the Money
The headline price is agreed, then the real work starts. Here is what buyers examine in due diligence, the problems that kill deals, and what to prepare a year in advance.
Founders imagine an acquisition as a handshake and a wire transfer. In reality, the handshake is the beginning of the most invasive examination your company will ever go through. Between the signed letter of intent and the money arriving sits due diligence: weeks or months in which the buyer's lawyers, accountants, and engineers go through everything you have ever done, looking for reasons to lower the price or walk away. Deals die here more often than anywhere else.
What the data room contains
Due diligence runs through a data room — a organized set of folders the buyer works through methodically. The categories are predictable, which means you can prepare them long before any buyer appears.
| Area | What the buyer checks | What kills deals |
|---|---|---|
| Corporate | Incorporation documents, board minutes, stock ledger | Missing signed documents, unclear share ownership |
| Financial | Three years of statements, revenue detail, tax filings | Revenue that does not match the pitch, messy books |
| Legal | Customer and supplier contracts, employment agreements, IP assignments | An early contractor who never signed over their work |
| Product and code | Code quality, dependencies, security, who wrote what | Code the company does not clearly own |
| Customers | Concentration, churn, contract terms, references | One customer that is 40% of revenue and month-to-month |
| People | Key employee agreements, visa status, who plans to stay | A technical cofounder with no obligation to remain |
The questions that kill deals
Most deals do not die from one dramatic discovery. They die from accumulation: small inconsistencies that make the buyer stop trusting the numbers. Revenue recognized differently than described in the pitch. A cap table that does not match the stock ledger. A "proprietary" product built largely on a contractor's unsigned work. A key customer who, when called as a reference, sounds lukewarm.
The single most dangerous pattern is surprise. A buyer who finds a problem you disclosed upfront prices it in and moves on. A buyer who finds a problem you hid — or genuinely did not know about — starts wondering what else is hidden, and the price drops or the deal dies.
How long it really takes
Plan for sixty to ninety days from letter of intent to close for a straightforward small acquisition, and longer for anything complex. The letter of intent usually includes an exclusivity period — often 45 to 60 days — during which you cannot talk to other buyers. That exclusivity is the buyer's leverage: if diligence drags past it, the price conversation reopens, and rarely in your favor. Momentum matters. Respond to requests within a day, and have the data room ready before the letter of intent is signed, not after.
What to prepare a year in advance
The founders who sail through diligence started a year early. Get every contractor and employee to sign IP assignment agreements — and find the old ones who never did. Clean up the cap table and make sure the stock ledger matches it. Move revenue recognition to something an accountant would recognize. Write down the informal arrangements: the handshake discount, the verbal partnership, the side agreement with a cofounder. And run your own mock diligence: have your lawyer and accountant play buyer and tell you what they would find.
The cost of diligence — and who pays it
Diligence is expensive even when it goes well. Legal and accounting fees for the seller commonly run into the tens of thousands of dollars, and the founder's time cost is larger still: for two or three months, a meaningful share of your attention goes to answering requests instead of running the company. Budget for both before you sign the letter of intent.
This creates a real risk founders underestimate: the deal distracts the business, the quarter softens, and the buyer uses the soft quarter to renegotiate. The defense is to keep the company performing. Delegate diligence responses to a small team — usually your lawyer, your accountant, and one trusted operator — and keep yourself focused on the numbers the buyer is watching. A deal that closes at the agreed price with a business that kept growing is worth far more than the hours you personally saved by answering every email yourself.
Also know what the buyer is spending. A serious buyer burns real money on diligence too — lawyers, accountants, sometimes technical reviewers. That sunk cost works quietly in your favor: a buyer deep into diligence wants to close. It does not protect you from a genuine problem, but it means small issues are usually priced or fixed rather than fatal, as long as you disclosed them early and honestly.
Finally, plan for the deal to fail. Until the money moves, keep the company running as if no offer exists: hiring, shipping, and spending as normal. Founders who put the business on hold for a deal that then falls through face the worst of both worlds — no exit and a stalled company.
Common mistakes
- Signing a letter of intent before the data room is ready.
- Hiding a problem and hoping it stays buried. It never does.
- Letting diligence stall. Every quiet week invites a price cut.
- Treating diligence as the buyer's problem. Speed and completeness are your job.
- Forgetting the team. Buyers are acquiring the people as much as the product; key employees need a reason to stay.
After the wire: the obligations that remain
Closing is not quite the end. Most acquisitions include an escrow or holdback — typically 10 to 15 percent of the price, held for a year or more against any problems that surface later — and many include an earn-out tied to future performance. The representations you made in the purchase agreement survive closing, so a sloppy answer given in diligence can come back as a claim against the escrow long after you have celebrated. Keep the diligence record: the data room contents, the disclosure schedules, and the questions you were asked. If a dispute arises two years later, that record is your defense. The founders who treat diligence as a one-time chore often learn this the hard way; the ones who treat it as building a permanent record of a clean company sleep much better after the wire arrives.
How the game models it
In Garage to IPO, acquisition offers reflect what is actually on your books: clean financials, owned code, and a stable team produce better offers than a flashy top line with chaos underneath. That is exactly how real buyers think. The headline number is negotiated in a day; what you actually keep is decided by what diligence finds.
Diligence is not a hurdle between you and the sale. It is the sale. Prepare for it like one.
Common questions
- How long does acquisition due diligence take?
- For a straightforward small acquisition, plan for 60 to 90 days from letter of intent to close. Complex deals take longer. Letters of intent usually include a 45 to 60 day exclusivity period, so delays work against the seller.
- What most often kills a deal in due diligence?
- Rarely one big discovery — usually an accumulation of small inconsistencies that erode trust in the numbers. The most dangerous are surprises: undisclosed problems, missing IP assignments, a cap table that does not match the stock ledger, or a key customer who sounds lukewarm on a reference call.
- When should a founder start preparing for due diligence?
- About a year before you expect to sell. Get IP assignments signed by every past contractor, reconcile the cap table and stock ledger, clean up revenue recognition, document informal arrangements, and run a mock diligence with your own lawyer and accountant.
Keep reading
Life After the Sale: Lock-Ups, Earn-In Years, and What Founders Do Next
The integration year, the money decisions that cannot be undone, and why the identity problem hits harder than the financial one.
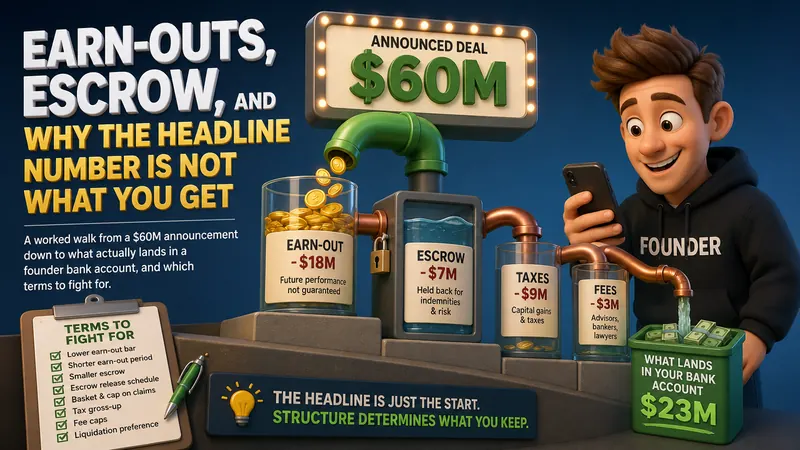
Earn-Outs, Escrow, and Why the Headline Number Is Not What You Get
A worked walk from a $60M announcement down to what actually lands in a founder bank account, and which terms to fight for.
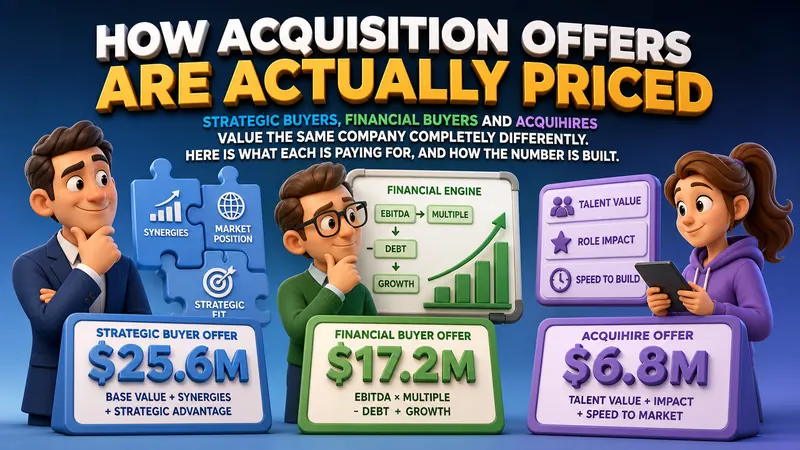
How Acquisition Offers Are Actually Priced
Strategic buyers, financial buyers and acquihires value the same company completely differently. Here is what each is paying for, and how the number is built.